
The worst outcome on a bitcoin-backed loan is not a high rate. It is being forced to part with your Bitcoin at the bottom of a drawdown because your loan-to-value ratio crossed a line. A margin call itself is only the warning. It is a notice that your LTV has risen past its threshold and that you need to act, either by adding collateral or by paying down principal. Liquidation is what follows when that call goes uncured. That sequence is the reason a lot of long-term holders never borrow against their coins at all.
SALT Shield® is our answer to that problem. In plain terms, it is an optional upgrade you buy once, for a one-time fee, and in exchange SALT agrees not to enforce its margin call liquidation rights on your loan for the remainder of the term. Your Bitcoin stays as Bitcoin through the maturity date, even in a deep drawdown.
This post explains how SALT Shield® actually works, what it costs, when to buy it, and just as importantly, what it does not do. The limits matter, and they are the part most borrowers do not read until they need to.
The Problem SALT Shield® Solves
Every collateralized loan has thresholds where the lender steps in. On a SALT loan there are three, and they escalate as your LTV climbs:
- Warning at 75% LTV or higher. An early notification that your position has moved into the range worth watching. No action is required.
- Margin call at 83.33% LTV or higher. A notice that you need to act. You can cure it by adding collateral or paying down principal to bring your LTV back below the threshold.
- Margin event at 90.91% LTV or higher. If the margin call has not been cured by the time this threshold is crossed, SALT can act on the collateral, either converting it to stablecoin through Stabilization or liquidating it.
Where that last threshold sits matters more than borrowers usually realize. At some lenders, liquidation can begin at an LTV as low as 80%, which means a moderate dip is enough to trigger forced selling. SALT does not reach a margin event until 90.91%, one of the highest thresholds in the industry, so borrowers get considerably more room before anything happens to their collateral. The stretch between the margin call and the margin event is your window to respond, and in a fast market that window can still close quickly.
The timing is the cruel part. Those thresholds are crossed precisely when Bitcoin is at its weakest, which means curing a margin call requires producing more Bitcoin or more cash at the exact moment both are hardest to part with. A borrower who is perfectly capable of repaying on schedule can still lose the asset they were trying to keep, simply because the market moved against them in the middle of the term and they could not cure in time.
SALT Shield® removes that specific outcome from the table. For a full explanation of how margin calls and LTV thresholds work, see our margin call guide.
How SALT Shield® Works
SALT Shield® is a contractual forbearance, which is a precise and important term. When you purchase it, SALT agrees that it will not enforce its margin call liquidation rights against your collateral for the covered period, typically through your maturity date, even if your LTV goes past the threshold. That includes not converting your Bitcoin into stablecoin through Stabilization.
The mechanics are straightforward:
- You buy it after your loan is funded. SALT Shield® is purchased after disbursement rather than at application, and it is optional. Expressing interest during the application does not reserve it.
- It carries a one-time fee. The fee is quoted at the time of purchase and that quote is valid for 24 hours. Pricing can move with market conditions, so any figure shown in the app or on the site is indicative until you buy.
- Activation takes up to two business days. Coverage begins once payment is received, processed, and the product is activated, which may take up to two business days.
- It must be purchased at least three months before maturity. You can upgrade any time up to three months before your loan matures. Inside that final three-month window, SALT Shield® is no longer available on the loan.
- It runs to maturity. Coverage continues for the rest of the loan term and terminates at the maturity date.
- It is Bitcoin only. SALT Shield® is available only on loans where the collateral is solely BTC.
Buy It Before You Need It, Not During the Drawdown
This is the single most practical thing to understand about SALT Shield®, so we will be blunt about it. If a margin event occurs before your SALT Shield® is activated, SALT reserves the right to refund the fee in full and treat the product as never purchased. The two-day activation window is real.
The same logic applies to the cancellation window. SALT Shield® is non-refundable once activated, with one exception: you may cancel within three days of payment for a full refund. But if a margin event occurs during those three days, the refund period ends at that moment and the fee becomes non-refundable.
The three-month deadline points the same direction. SALT Shield® is something you put in place while conditions are calm, as part of structuring the loan, not something you reach for when the chart is already falling. Borrowers who wait for volatility to decide often find they have waited too long, either because the market moved first or because the loan is already inside its final three months.
SALT Shield®Compared to Stabilization and a Standard Loan
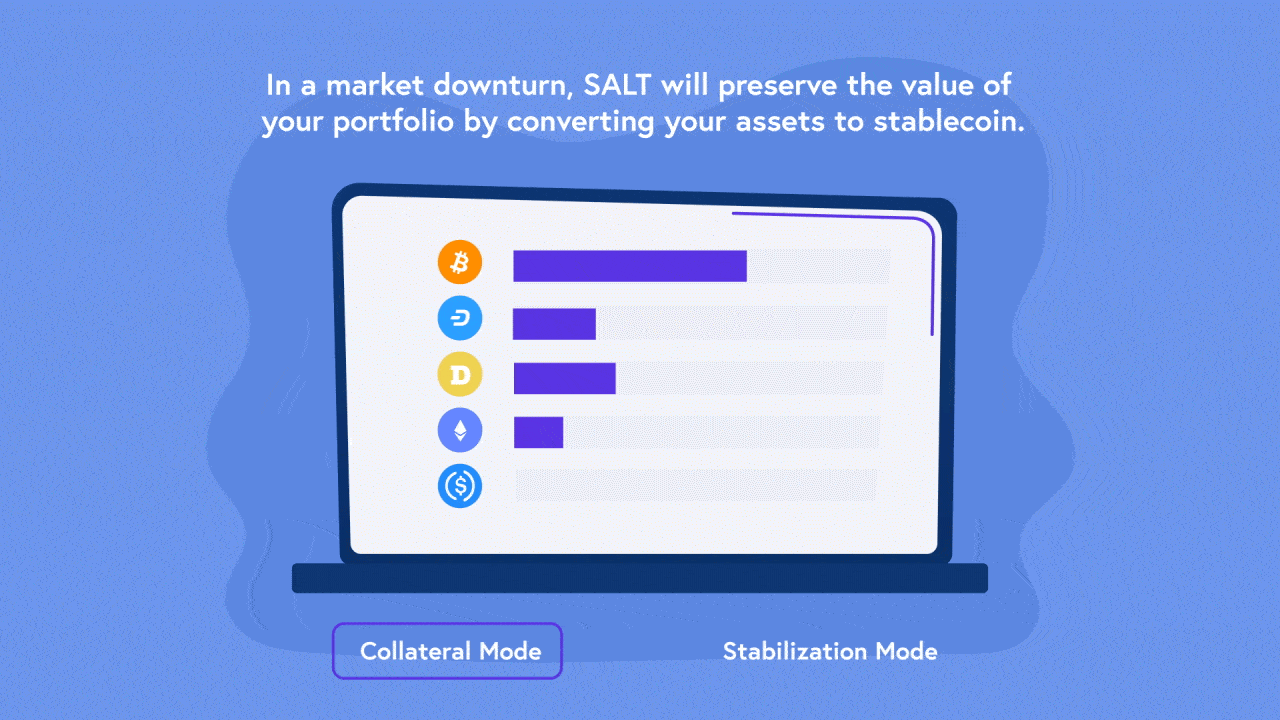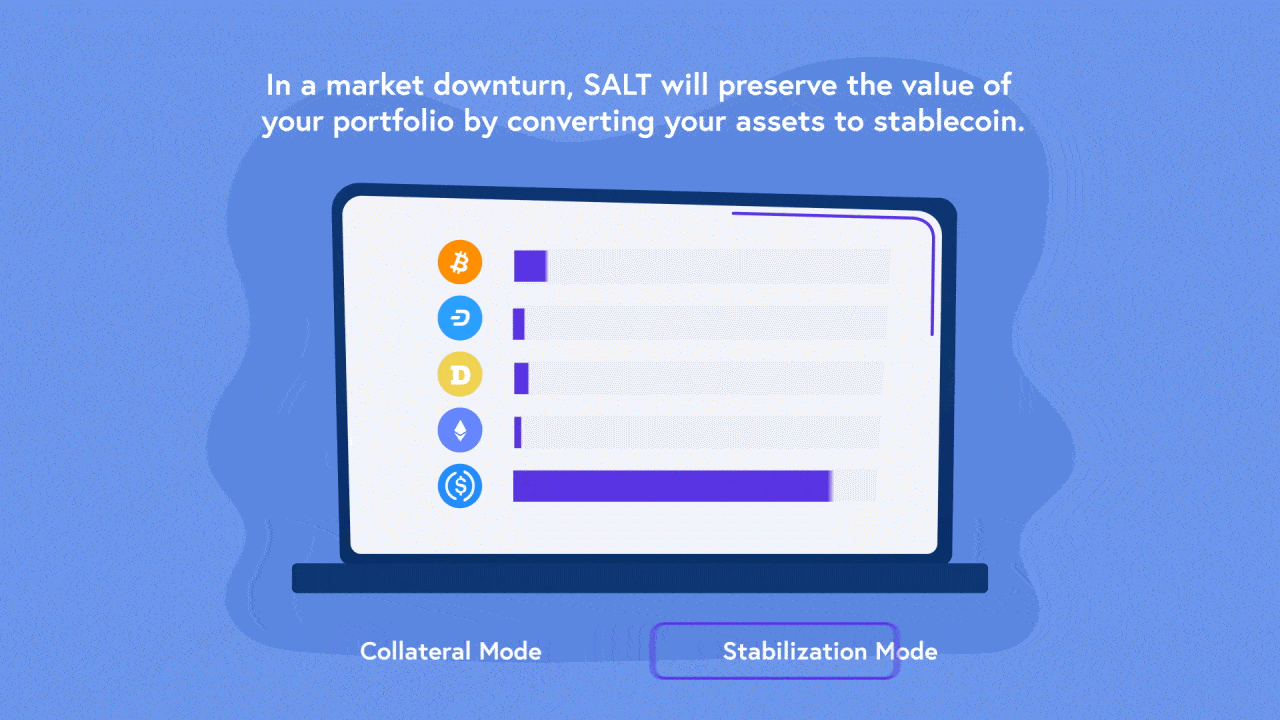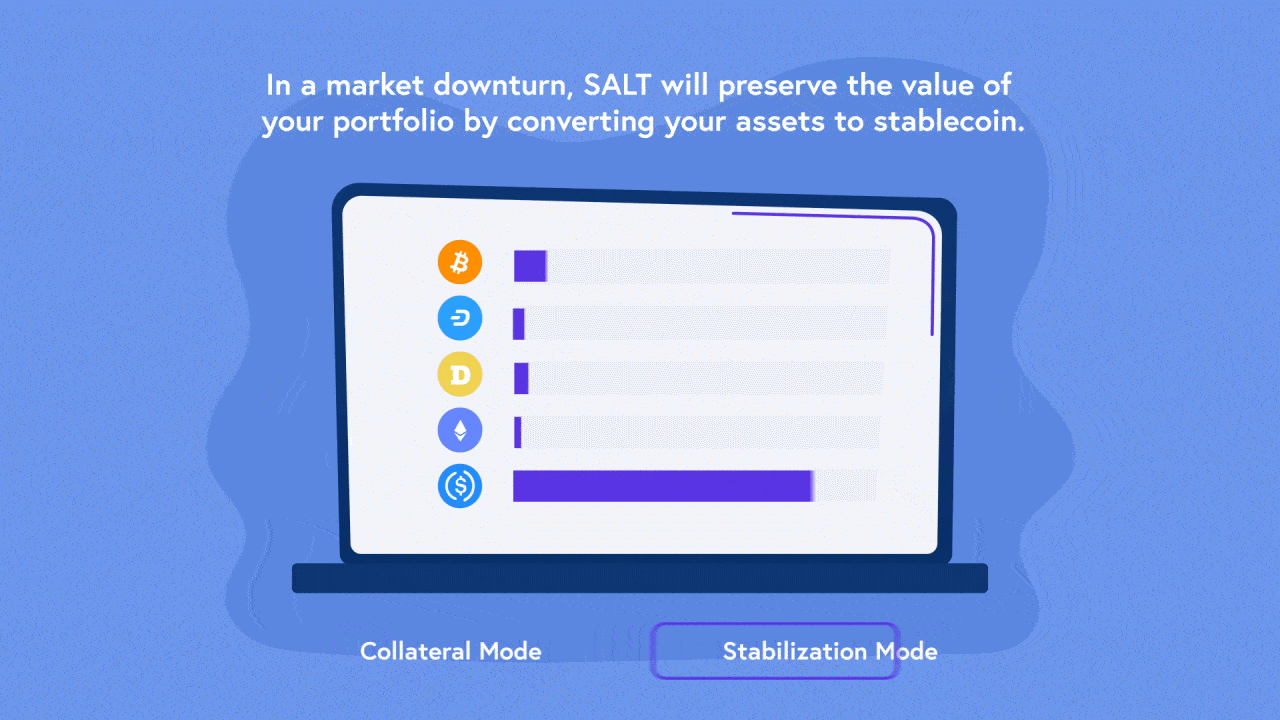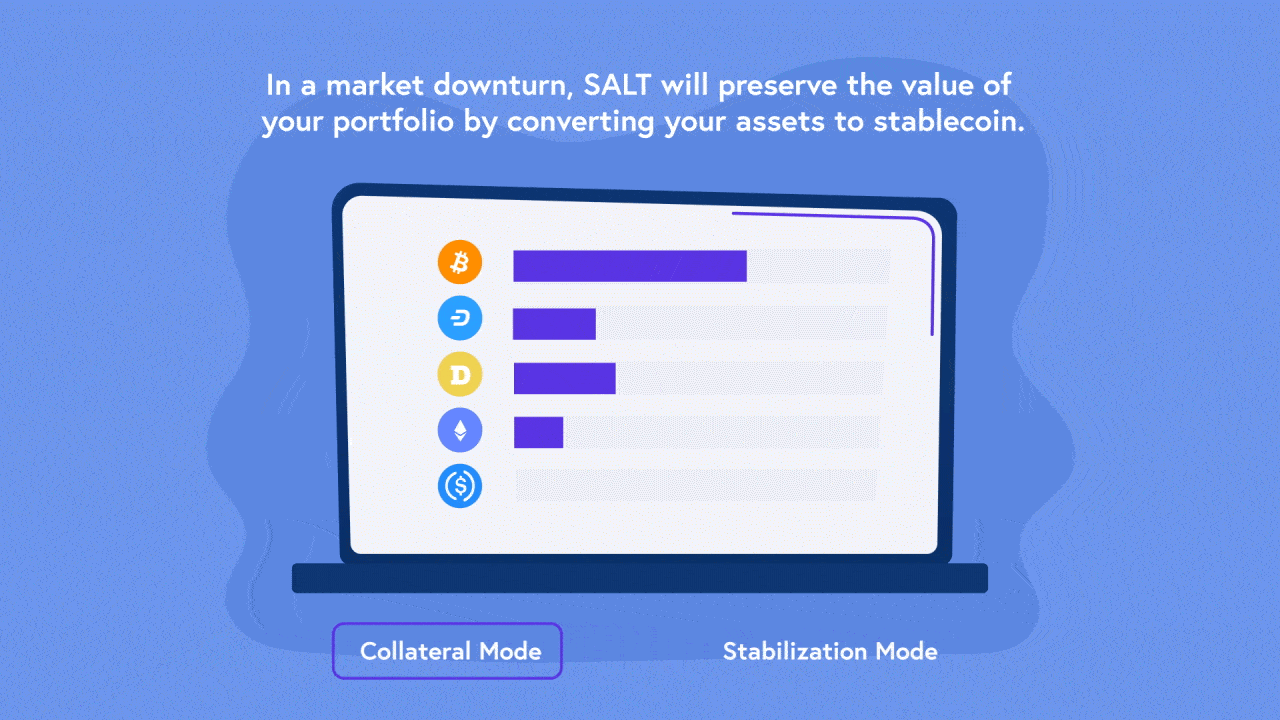
SALT has two different tools for handling downside, and they work in opposite ways. Stabilization preserves the dollar value of your collateral by converting it to USDC when LTV reaches the threshold. SALT Shield® preserves the Bitcoin itself by declining to act at all.
| Standard Loan | Stabilization | SALT Shield® | |
|---|---|---|---|
| If LTV reaches 90.91% (margin event) | If the margin call was not cured, collateral may be converted or liquidated | Collateral automatically converts to USDC to lock in value | SALT forbears from enforcing margin call liquidation rights |
| Collateral stays in Bitcoin | Not guaranteed in a downturn | No, it becomes a stablecoin position | Yes, through the maturity date |
| Cost | None | None | One-time fee quoted at purchase |
| Collateral withdrawals during the term | Permitted subject to LTV | Permitted subject to LTV | Not permitted until maturity |
| What you owe at maturity | Unchanged | Unchanged | Unchanged |
Which one fits depends on what you are actually trying to protect. If your priority is the dollar value of the position, Stabilization does that job and gives you the option to convert back later. If your priority is coin count, and the thought of your Bitcoin being sold at a cycle low is the thing keeping you out of a loan entirely, SALT Shield® is the product built for you. Our Stabilization explainer covers that side in more detail.
What SALT Shield® Does Not Do
SALT Shield® is narrow by design, and being clear about its limits is more useful than overselling it. Six things it does not do:
- It is not insurance. SALT Shield® is a temporary forbearance of SALT’s margin call enforcement rights for a fixed period. It is not an insurance product and does not provide coverage against loss in the way an insurance policy would.
- It does not reduce what you owe. Your interest, principal, and other loan obligations are unchanged, and the full balance is due at the maturity date regardless of what your LTV happens to be at that point.
- It does not let you withdraw collateral. Once SALT Shield® is purchased, collateral withdrawals are not permitted until maturity, regardless of LTV. If flexibility to pull collateral out mid-term matters to you, this is a real trade-off.
- It does not guarantee a refinance. Refinancing at or before maturity still requires that the LTV requirements for that refinance are met.
- It does not stop the notices. SALT may continue to send margin notices about your LTV even while SALT Shield® is active, so you will still see where your loan stands.
- It is not available everywhere or on every loan. SALT Shield® is not offered in every jurisdiction where SALT lends, is not available below a required loan minimum, and SALT may decline to offer it. Check current availability at saltlending.com/map-list.
The honest way to summarize all of that: SALT Shield® does not eliminate the risk of a leveraged position. It moves the decision point to your maturity date and takes forced selling off the table in between. That is a meaningful thing to buy, and it is a different thing from a guarantee.
Planning for the Maturity Date
Because SALT Shield® terminates at maturity, the maturity date is where your planning should focus. If Bitcoin has fallen sharply during your term and your LTV is elevated when the loan comes due, you have the same set of options any borrower has: repay in full from other funds, repay in part and refinance if you meet the LTV requirements at that time, or work with the loan team on what is available.
One detail worth knowing in advance. If you ask SALT to liquidate your collateral to pay off the loan early, that request will be declined when the collateral is not sufficient to repay all obligations in full, meaning LTV of 100% or higher. SALT Shield® keeps your Bitcoin intact, and the obligation stays intact alongside it.
If you refinance a SALT Shield® loan into a new loan with additional principal more than 30 days before maturity, you may receive a credit toward SALT Shield® on the new loan, calculated as days remaining to maturity divided by 365, multiplied by half of your existing SALT Shield® fee. The credit applies only if you purchase and activate SALT Shield® on the new loan within three business days of the new loan commencing.
Who SALT Shield® Makes Sense For
SALT Shield® is not the right purchase for everyone. It tends to make sense for:
- Long-term holders whose primary goal is keeping coin count intact through a full cycle
- Borrowers at higher LTV, where a moderate drawdown is enough to reach the threshold
- Anyone who would otherwise not borrow at all because margin call risk is a dealbreaker
- Borrowers who will not need to withdraw collateral before maturity
It makes less sense for borrowers at very conservative LTV who already have a deep cushion, for anyone who expects to add or remove collateral during the term, and for borrowers who intend to repay quickly, since the fee is not refunded on prepayment.
Frequently Asked Questions
Is SALT Shield® insurance?
No. SALT Shield is a contractual agreement by SALT to forbear from enforcing its margin call liquidation rights for a fixed period. It is expressly not insurance and does not provide coverage against loss in the insurance sense. It addresses one specific risk, which is forced selling triggered by price movement.
How much does SALT Shield® cost?
SALT Shield® carries a single one-time fee rather than an ongoing charge. The amount depends on your loan and current market conditions, and it is quoted to you at the time of purchase. That quote is valid for 24 hours. Any pricing shown in the app or on the website beforehand is indicative and subject to adjustment.
Can I add SALT Shield® to a loan I already have?
Yes. SALT Shield® is purchased after your loan has been disbursed, so existing borrowers can add it to an active loan, provided the loan is more than three months from its maturity date. Log in to your SALT account to see whether it is available on your loan and what the current fee is.
Does SALT Shield® mean I can never lose my Bitcoin?
No, and it is important to be precise here. SALT Shield® means SALT will not force-sell your collateral due to price movement during the covered period. You still owe the full loan balance at maturity, and what happens after maturity depends on whether that obligation is met. SALT Shield® removes forced selling during the term, not the obligation itself.
Can I withdraw collateral while SALT Shield® is active?
No. Once SALT Shield® is purchased, collateral withdrawals are not permitted until the maturity date, regardless of how favorable your LTV becomes. This is the main trade-off of the product and worth weighing before you buy.
Is SALT Shield® available on Ethereum or other collateral?
No. SALT Shield® is available only on loans collateralized solely by BTC. If you are borrowing against ETH or a mix of assets, SALT Shield® is not available on that loan.
What happens to SALT Shield® when my loan matures?
SALT Shield® terminates at the maturity date. If you refinance into a new loan, SALT Shield® is not carried over automatically, though a credit toward SALT Shield® on the new loan may apply in certain refinancing situations.
Can I get a refund on the SALT Shield® fee?
SALT Shield® is non-refundable, with one exception. You may cancel within three days of payment for a full refund, unless a margin event occurs during that window, in which case the refund period ends at that moment. Repaying your loan early does not result in a refund of any part of the fee.
The Bottom Line
SALT Shield® does one thing and does it clearly: for a single fee, it takes forced liquidation off the table for the rest of your loan term, and your Bitcoin stays Bitcoin. It does not change what you owe, it locks your collateral in place until maturity, and it ends when the loan does.
For a long-term holder who wants liquidity without the risk of being sold out at the bottom, that is a trade worth understanding. Log in to your SALT account to see whether SALT Shield® is available on your loan, or review the full terms before you buy.
Disclosures
SALT Shield® is a proprietary product of SALT Lending LLC. It represents a temporary forbearance of Lender’s right to enforce margin call rights under the Loan Documents for a fixed, predetermined period of time. SALT Shield® is not insurance, nor an insurance product, and no representation is made that it is insurance against, or coverage for, any risk of loss.
SALT Shield® does not alter any of Borrower’s payment obligations in respect of interest, principal, or other Loan Obligations. Borrower is obligated to pay all Loan Obligations at the Maturity Date regardless of then-current LTV. SALT Shield® terminates at the Maturity Date. This article summarizes the product for informational purposes only and is not a complete statement of its terms; the SALT Shield® Terms and Conditions and your Loan Documents govern in all cases.
Availability and pricing are based upon loan-specific terms and conditions, LTV minimums, term length, jurisdictional restrictions, and other requirements, and are subject to change. SALT Shield® is not offered in every jurisdiction where SALT lends and is not available for Loans below a required Loan minimum. Lender reserves the right to offer or not to offer SALT Shield® with respect to any Borrower or any Loan at any time, to adjust the product offering, or to alter pricing or other terms. For current jurisdictional availability, see saltlending.com/map-list.
Borrowing against collateral entails risk and may not be appropriate for your needs. Rates and terms for SALT products are subject to change. Digital currency is not legal tender, is not backed by the United States or any other government, and SALT accounts are not subject to FDIC or SIPC protections. Loan terms may vary or may not be available in your jurisdiction, for your requested loan amount, or for your preferred collateral type.
Nothing in this article constitutes investment, financial, trading, legal, or tax advice, and nothing herein should be construed as an offer, sale, endorsement, or recommendation regarding any security or digital asset. You are encouraged to conduct your own research and to consult your financial, tax, or legal advisors before making any decisions.
SALT loans are originated by SALT Lending LLC (f/k/a SALT Master Fund II, LLC), NMLS 1711910. Loans are issued pursuant to private agreements. You should review the representations, warranties, and other terms and conditions described in the loan agreement.